


Qatar Islamic Bank
 QIB Mobile








Publisher DNA
What defines Qatar Islamic Bank?
AI intelligence is not yet available for Qatar Islamic Bank. The portfolio data below is up to date.
Portfolio
What does Qatar Islamic Bank ship?
Apps
8 apps analysed

Analysis in progress

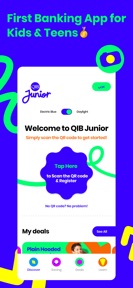

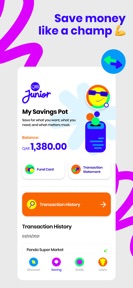
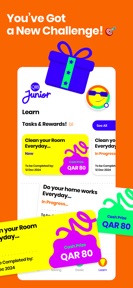
Task-based pocket money creates a recurring engagement loop between parent and child
- The digital card interface provides a rewarding experience for younger users within the banking environment
- Extended loading times on the initial splash screen frustrate users during the daily login process

Analysis in progress


Analysis in progress
QIB Mobile App allows you to enjoy the convenience of banking anytime, anywhere.


Analysis in progress
Single-market publisher, every app ships only to United States.
Based on 2 of 8 apps with localized market data, more coverage rolling in as scans complete · last scanned .
Americas (1)
- United States2 / 2
Core markets (2/2 apps)
User Sentiment
How do users feel about their apps?
1
Positive apps
1
Neutral / mixed
0
Negative apps
66/100
Avg sentiment score

Rivals
Who does Qatar Islamic Bank compete with?
The rivals identified
Nemeses(1)

Both apps serve as primary digital portals for retail banking, competing for user attention by balancing transactional utility with account management.
Contenders(9)


Both apps serve as primary mobile banking portals for existing customers, competing for daily engagement through account management and payment modules.


Both apps serve as primary mobile banking portals for existing customers, competing for user retention through account management and transaction authorization features.


Both apps function as primary mobile banking portals for existing bank customers, competing for daily active usage through core account management and payment features.


Both apps function as primary digital banking channels for their respective customer bases, competing for user attention through core account management and payment features.


Lloyds Mobile Banking competes for the same mobile banking user segment by offering end-to-end digital account opening and subscription management, directly challenging the manual financing processes found in QIB Mobile.


Both apps serve as primary digital banking interfaces for retail customers, competing for user attention through account management and payment features.


Both apps function as primary digital banking portals for existing customers, competing for daily engagement through account management and payment services.


Both apps function as primary digital banking interfaces for personal account management, competing for user attention by offering card controls and payment features within the mobile banking category.


Both apps function as primary digital banking portals for existing customers, competing on the ability to manage accounts and execute routine financial tasks.
Same space(6)


Consors Finanz shares QIB Mobile's focus on credit management while highlighting the negative impact of restrictive verification on user sentiment.


CB Waseet provides a specialized investment layer for Qatari banking customers, addressing the investment-focused gap identified in QIB Mobile.


Creation Finance acts as a specialized utility for retail credit agreements, similar to QIB Mobile's role in managing financing for existing customers.


Fifth Third represents a traditional retail banking model that QIB Mobile mirrors, focusing on core account management and check deposits.


Monzo Bank serves as a global benchmark for neobank feature sets, highlighting the gap in QIB Mobile's digital financing and budgeting tools.


Virgin Money demonstrates the risks of a mobile-only strategy for credit card servicing, mirroring QIB Mobile's struggle with technical stability.
